
Ah, the age old question when it comes to how best to invest your money – should you invest in stocks or in property? I have no doubt that the answer comes down to personal preference. However, based on my experience (and I have experience with both investment methods), I much prefer stocks over real estate. Here’s why:
The real investment is not money – it’s time
Investing is not just about where you choose to put your money – it’s also about how you choose to spend your time. Investing money also requires that you invest some of your time in order for that investment to become successful. Time and money are two sides of the same coin. However, the time requirement varies from investment to investment. It’s very easy to be caught out by the time requirement that some investments demand, given that all the focus on the financial returns.
As someone who prioritises time and health as the ultimate currencies of life, I prefer to choose the easiest form of investing that requires the least effort. This allows me to live life without spending unnecessary mental effort thinking about my investments. Owning a rental property requires quite a bit of effort – both physical and mental.
My investment property
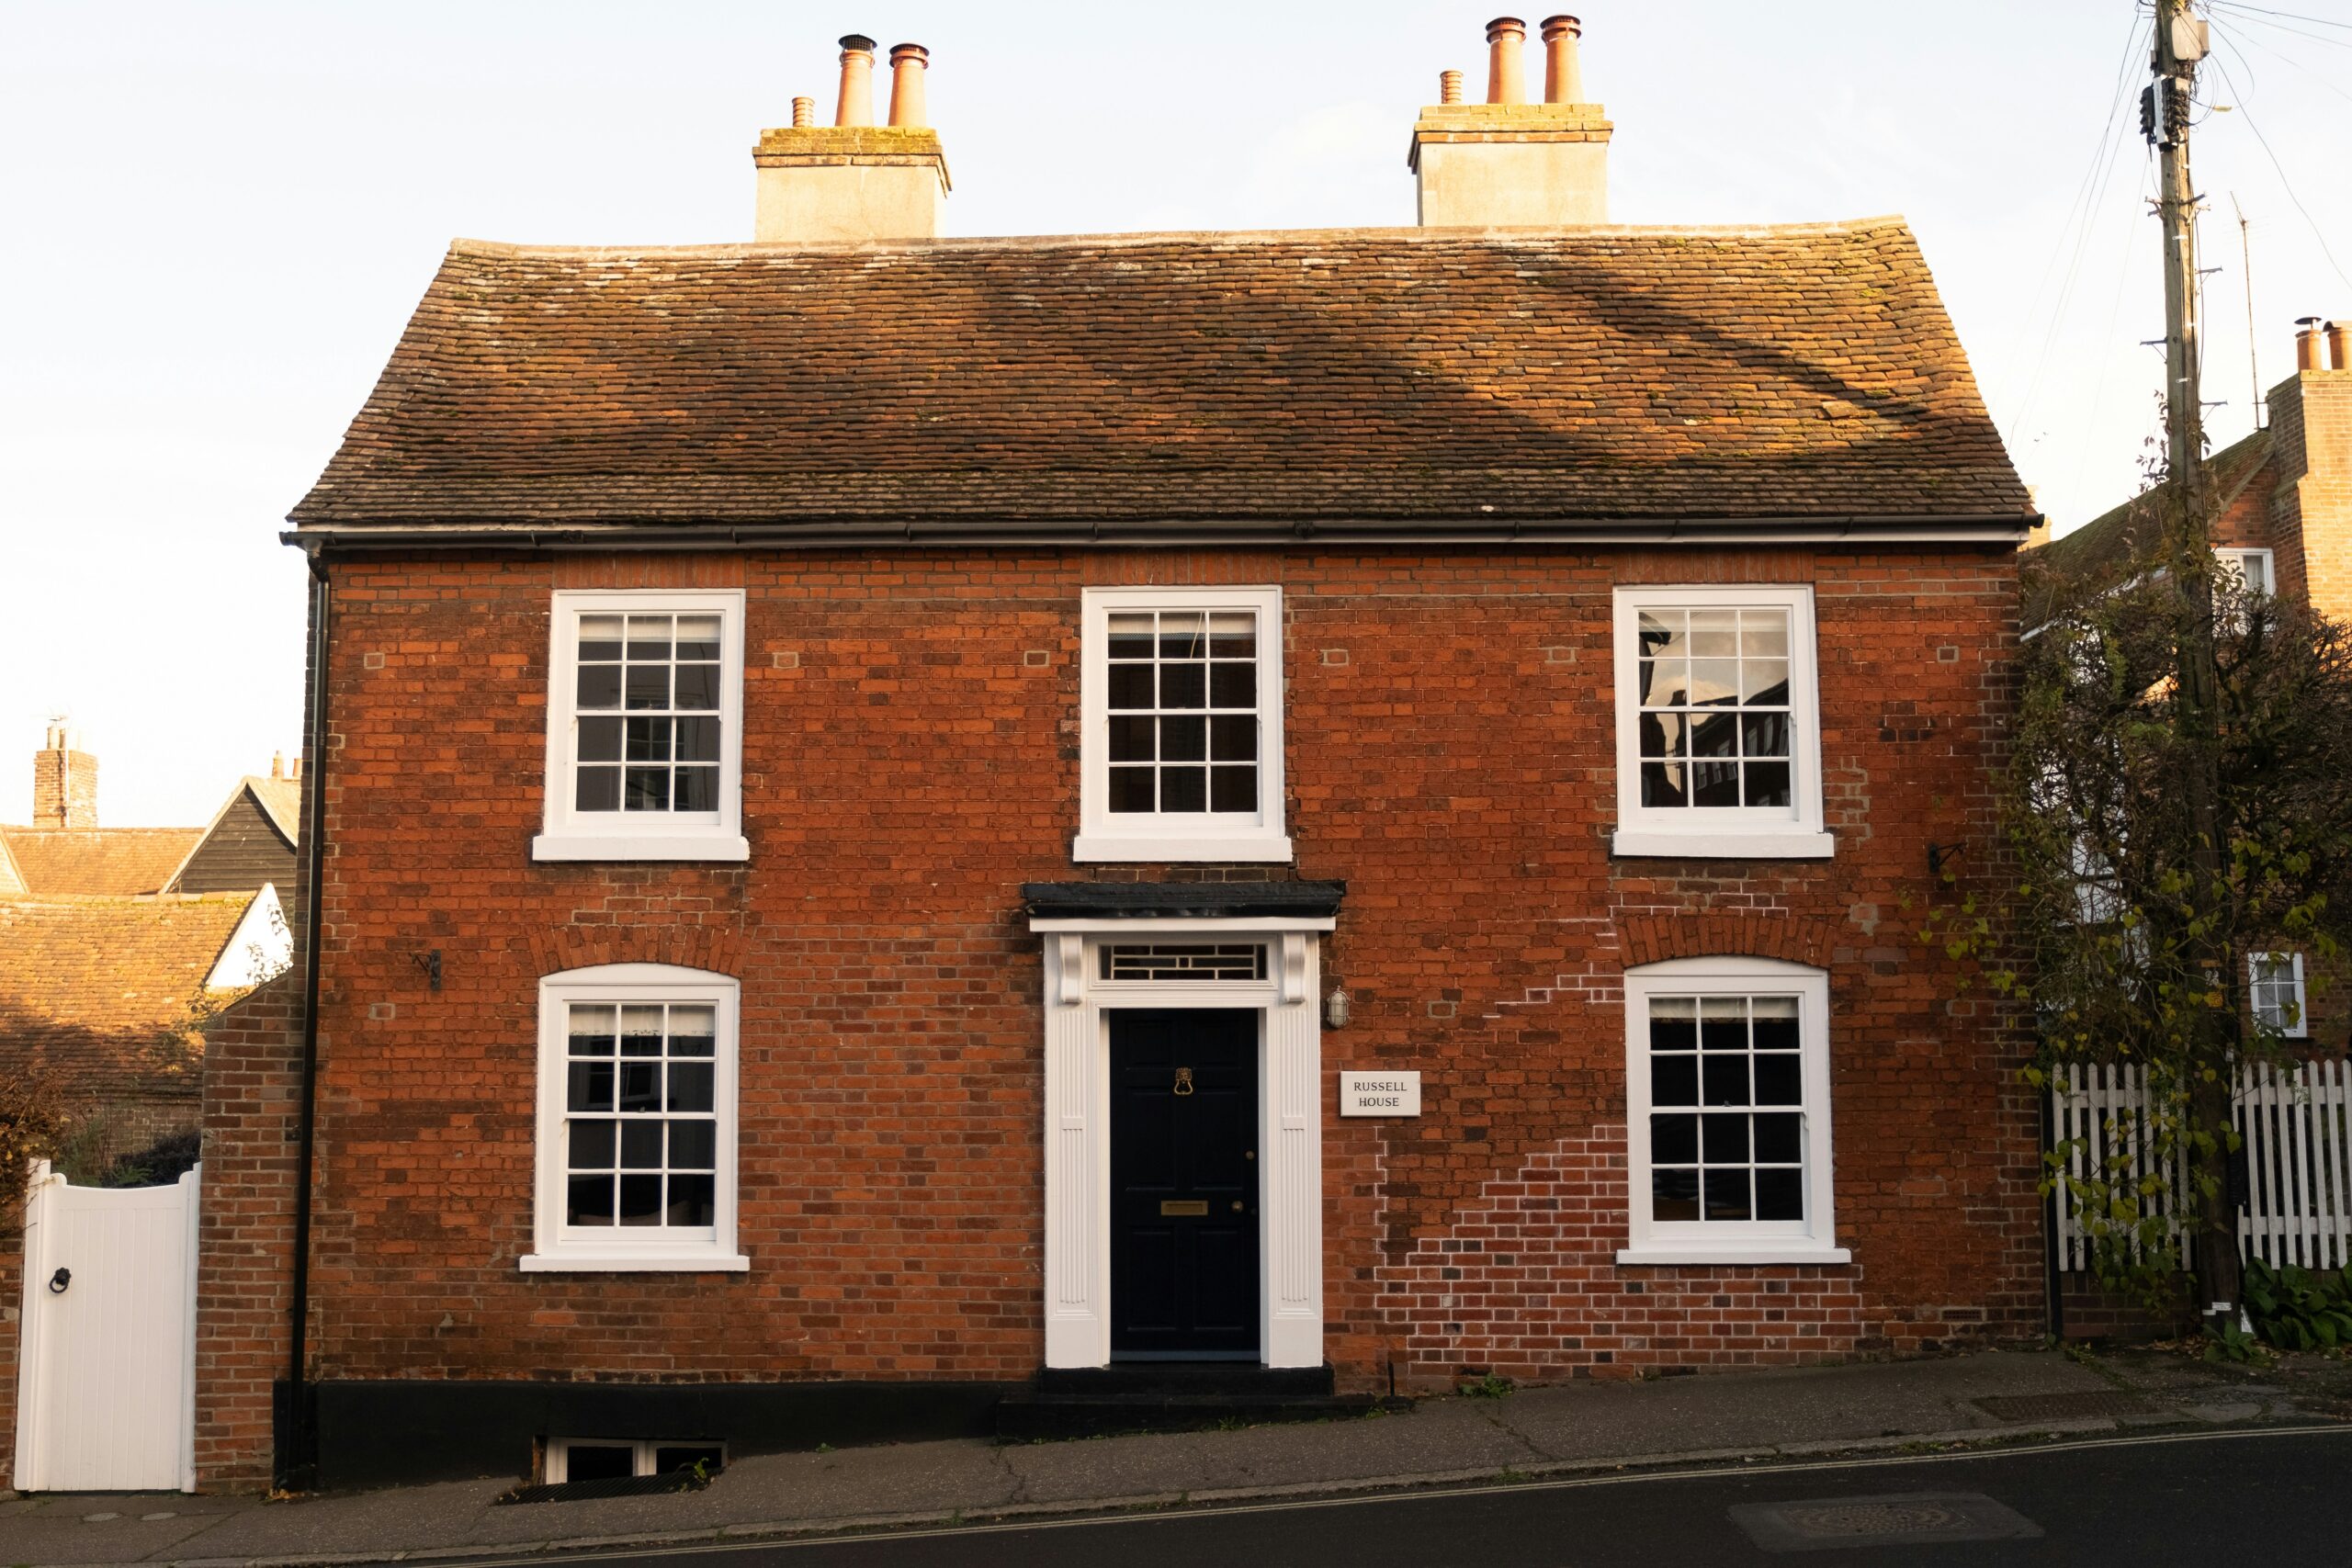
It was an old three bedroom terraced house from the late 1890s, set into the side of a hill in an English village. “What a dream” you may think. Ah yes, but all that glitters is not gold. Although the house was pretty, I don’t think any sane person would call it a good investment. It was an old house, and that meant it had problems. Lots of them. From subsiding brickwork, to a poorly tiled roof, to a damp kitchen and even nesting birds in the loft – there was always something to deal with.
Along with some eye-watering expensive work that needed to be done to the retaining wall around the garden, I actually ended up at a slight loss over the 5 years I held it as a rental property. The fact that the retaining wall needed to be replaced was bad luck (it was original and there was a high risk of it collapsing completely, burying any cars parked underneath it and blocking the main road) – but works like this are very real costs that needs to be considered when owning an old property.
Will house prices go up in value?
“Okay”, you may ask, “while buying an old house as a rental may have higher maintenance costs, you can still bet on the house value increasing over time.”
Despite stabilising from historic highs in 2021, house prices in the UK remain very high relative to the long-term average, and average wages. I do not think it is a guarantee that inflation-adjusted house prices will continue to increase. After all, people still need somewhere to live, and there is only so much they can afford to pay. Remember that a house is only worth as much as people are willing to pay for it, and prices can only get so high before people stop buying them. I believe we are close to that threshold.
Average house prices have had a very strong run in the UK over the past 20 years (86.5% increase since 2006) – an annual average of 3% per year. This is versus 87.8% inflation in that time (an annual average of 3.2% per year). Meanwhile, the S&P500 has increased by 771.8% in that time, or 11.05% per year.
The time-value proposition
Here’s the thing – real estate requires you to deal with general maintenance, estate agents, mortgage advisors, insurance companies, councils, utilities providers and showing prospective tenants around – amongst the many other things that may occasionally crop up.
Are you going to deal with maintenance issues yourself? This requires a (potentially significant) investment of your time, while the alternative is to outsource the property management to an estate agent who will have contractors deal with any issues on your behalf. This takes the day-to-day property management largely out of your hands, but is vastly more expensive (I was paying a 12.5% management fee).
Granted, many (most) of these issues can be tamed by making a more considered rental property purchase in the first place – a newer house with no immediate issues, or perhaps even a commercial let (where the renter, unbelievably, pays you money and is still responsible for the day-to-day maintenance).
Of course, you can go the other way if you’re happy to put even more effort in. You can buy a “fixer-upper” (an old, crappy house that needs work done to it), do the work and then rent it out (or sell it) for a profit. But this requires a lot of work, and often morphs into a full-time job or business.
Even owning a newer property with a management company doing most of the work for you, you’ll still be responsible for authorising any contractor work needed, nor will you be completely removed from the legal processes and paperwork. And there will be a periods of time, potentially months, in-between tenants, when you’re not receiving any income at all.
Stocks are less effort
Investing your money more traditionally in stocks can be a lot less involved (although it doesn’t have to be). I’m a big fan of low-cost passive index fund investing, and this table illustrates why:

Pick stocks at your peril
Traditional stock picking can deliver extremely high annual returns (15%+ in some cases), but only the absolute best investors can consistently deliver this over many decades (think Warren Buffett, Peter Lynch). The rest of us might have one, two or three good years, but eventually will fall victim to our own egos – believing that several years of good (potentially market-beating) returns means the common denominator for this success is our own skill, rather than just dumb luck.
Eventually, you’ll stop getting lucky, and will be left burning at the side of the road, as one bad year – and that’s all it takes – completely wipes you out.
Always remember Buffett’s first two rules of investing:
- Rule number 1: Never lose money.
- Rule number 2: Never forget Rule number 1.
The reality of stock picking is that few people can consistently beat the market. Those that do are the world’s best investors (not you and I), have decades of experience, and devote their whole careers to the job. This is not something you can do at the kitchen table on the weekends – those that do are eaten for breakfast by the professionals.
Actively managed mutual funds are for fools
Actively managed mutual funds allow diversification of risk across entire sectors and economies – sometimes even the global economy. This is why they are a favourite amongst pension fund providers. They are actively managed by the fund managers – whom you are paying – while failing to consistently beat the market average stock market return.
Not only are you paying for a service that underperforms, you still need to monitor that the fund managers are doing a good enough job, and occasionally undertake research to see if there are any “superior” funds you should invest in. However, years of doing this and failing to match the market returns will eventually lead you to an epiphany:
Passive index fund investing
This approach suits me the most, because I did my research years ago on how I wanted to invest – super low cost Vanguard index funds like the Vanguard FTSE All-World UCITS ETF, and the Vanguard S&P500 UCITS ETF – and I now simply have a direct debit set up to invest a pre-determined amount of money into these funds once a month – and I forget about it. This approach has worked wonderfully. Because these funds don’t bother trying to outperform the market – they just buy the market – returns are better than about 90% of mutual funds over 10+ years.
I barely even think about my investments, look at them maybe 6 times per year, and otherwise take a completely hands-off approach. I trust capitalism with my money. As JL Collins said: “it’s a rollercoaster ride, with some bumps and dips along the way – but a rollercoaster which always, relentlessly – goes up”.
Because I value time very highly, having such a hands-off investment approach suits me very well. My investments sit quietly in the background, and continue to give a (market average) return of somewhere between 7-10% per year, on average. This gives me more time to work on my life – to advance my career, focus on my health and fitness, build this website and spend time with my family and friends. I can’t ask for more than that.
Hungry for more? Here are some other articles you may like:
- Vanguard lowers fees again!
- Can a Cheap Index Fund Really Beat the World’s Best Investors?
- The Little Book of Common Sense Investing
- VO2 Max: The Ultimate Health Metric and How to Measure it
- The Best Way to Spend Tesco Clubcard Points (February 2026)
You can follow me on X, and find me on Pinterest, Instagram and Facebook.
Leave a Reply